Outsourced accounting for property management companies in Orange County solves the back-office bottleneck that stalls growth: messy trust ledgers, late owner statements, and audit risk. REA pairs Orange County property managers with dedicated accountants who handle trust reconciliation, disbursements, and reporting inside your existing Property Management software stack.
By REA Team, Property Management Experts
Outsourced Accounting for Property Management Companies in Orange County: What It Solves
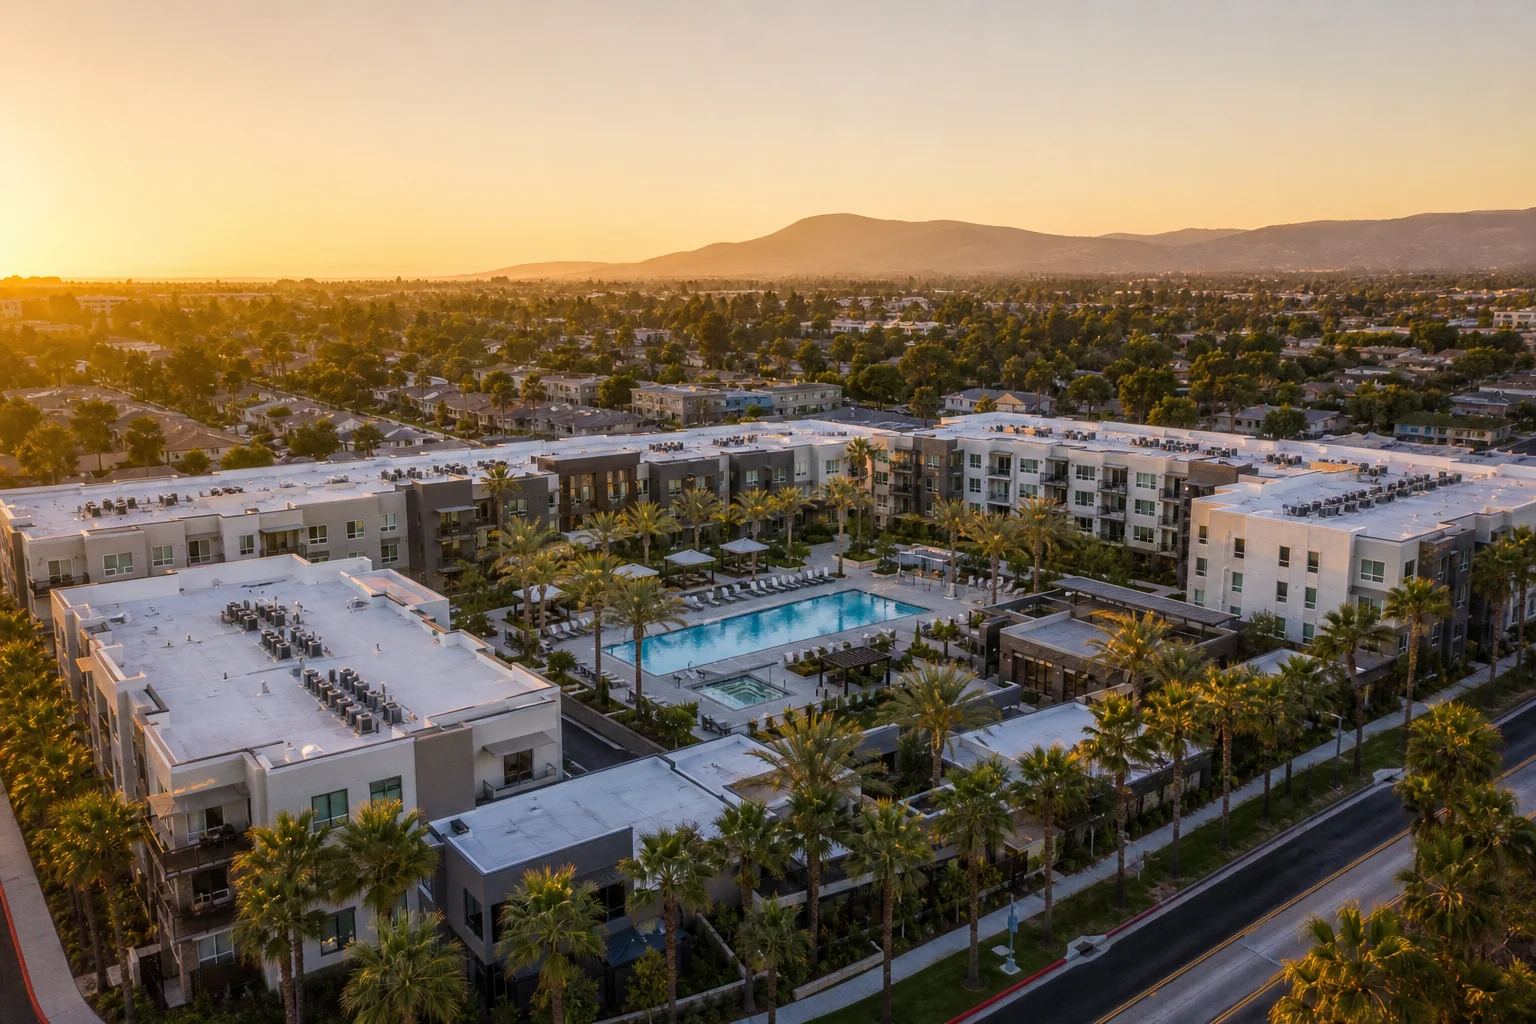
Property management firms across Orange County, from Irvine and Santa Ana to Anaheim and Newport Beach, are managing more doors with leaner back offices. Hiring an in-house controller who understands real estate specific trust accounting, owner reporting, and California disclosure rules is expensive and slow. That is why outsourced accounting for property management companies in Orange County has become the default move for firms that want to scale without adding payroll risk.
REA's accounting services help Orange County property managers replace reactive bookkeeping with proactive financial reporting, cash flow visibility, and advisory services that support long-term growth, not just monthly compliance. Instead of training a generalist bookkeeper on the nuances of trust fund handling, a property management company can hand that specialized work to a firm built around it, freeing internal staff to focus on leasing, maintenance, and tenant relations.
If you are not sure whether your firm has hit that point yet, watch for late owner statements, trust ledgers that will not reconcile cleanly, and staff spending more time fixing books than serving owners, the common warning signs that a portfolio has outgrown its back office.
California Trust Account and Escrow Rules for Property Managers
California treats trust funds as a strict compliance area, not a bookkeeping preference. Any property management company acting as a real estate broker and handling rent, security deposits, or owner funds on behalf of clients must keep those funds in a separate trust account, apart from the company's own operating account. The Department of Real Estate expects those accounts reconciled regularly, with underlying records kept organized and available for examination.
For Orange County property managers overseeing dozens or hundreds of units across scattered ownership groups, that means every dollar collected has to be traceable back to a specific owner and a specific property at any point in time. An outsourced accounting for property management companies in Orange County engagement builds that traceability into the monthly close instead of trying to reconstruct it after a DRE inquiry lands. REA's accounting specialists structure the chart of accounts and trust ledgers to match those expectations from the first month of onboarding.
Three-Way Trust Reconciliation Explained
Three-way trust reconciliation is the core control that keeps a property management company's books defensible. Every month, three numbers have to match exactly: the bank statement balance for the trust account, the book balance in the property management software, and the sum of every individual owner and tenant ledger inside that account. When those three figures tie out, you have documented proof that no owner's funds are commingled with another's and that the trust account is not being used to cover a shortfall.
When the three figures do not tie out, the gap usually traces back to a timing difference, a misapplied payment, or a missing bank fee, and it needs to be resolved before the next round of owner statements goes out. Firms that skip this discipline are the ones left explaining a shortage to a client or a regulator instead of catching it internally. An outsourced accounting services provider runs this reconciliation as a standing monthly deliverable, not an annual scramble.
Owner Statements, Disbursements, and 1099 Preparation
Owners expect clear, timely statements that show rent collected, expenses paid, management fees, and the net amount disbursed to them each month. Property management companies that outsource this function typically see statements go out on a consistent schedule instead of drifting later each cycle as internal staff get pulled into leasing and maintenance emergencies.
At year end, that same ledger data feeds directly into 1099 preparation. Property managers generally issue a 1099-MISC to each owner for rental income collected on their behalf and a 1099-NEC to vendors and contractors paid above the IRS reporting threshold. Getting those forms right, and out on time, depends entirely on whether the trust ledgers were accurate all year. Our Income Tax Services team handles that filing as part of the same engagement, so nothing falls through the gap between bookkeeping and tax.
California Security Deposit Law and Software Compatibility
California Civil Code Section 1950.5 governs how security deposits are collected, tracked, and returned to tenants, including requirements around itemized deductions and move-out documentation. Every deposit held has to be tracked at the unit level inside the trust account, and any deduction taken at move-out needs a paper trail an owner, a tenant, or a court can follow. Orange County's mix of long-term rental housing and higher-turnover multifamily communities makes this a daily occurrence rather than an occasional edge case.
Homeowners associations and community management companies face many of the same trust accounting and assessment tracking requirements as traditional rental property managers, which makes Orange County's dense mix of HOA communities and multifamily portfolios a natural fit for a single outsourced accounting partner.
Platforms We Work Inside
None of this compliance work depends on which software a property management company runs. REA's accounting teams work inside AppFolio, Yardi, Buildium, Rent Manager, Entrata, and QuickBooks every day, so onboarding does not mean migrating platforms or retraining staff on new systems.
The same trust accounting discipline that works for a property management firm in Los Angeles applies here, adapted to California's specific rules on trust funds, security deposits, and broker accountability. A closer look at a comparable coastal market shows how that build-out plays out for a similarly dense, high-turnover portfolio.
Frequently Asked Questions
Does outsourcing our accounting affect who is legally responsible for trust funds in California? No. The broker of record or qualifying individual for your property management company remains legally responsible for trust fund compliance under California law. An outsourced accounting for property management companies in Orange County engagement supports that responsibility with accurate books, monthly three-way reconciliation, and audit-ready records, but licensing accountability stays with your firm, not with REA.
Which property management software does REA support in Orange County? REA's accounting teams work directly inside AppFolio, Yardi, Buildium, Rent Manager, Entrata, and QuickBooks, so onboarding does not require migrating your property management company to new software. We adapt our trust accounting and reporting processes to whatever platform your Orange County portfolio already runs on, with no disruption to owners or tenants.
What is three-way trust reconciliation and why does it matter? Three-way reconciliation confirms that your trust account bank balance, your book balance, and the sum of every individual owner and tenant ledger all match each month. When those three figures agree, your property management company has documented proof that no client's funds are commingled with another's, which is exactly what a California DRE review looks for first.
How does outsourced accounting handle 1099 filing for owners and vendors? Your outsourced accounting team pulls disbursement and vendor payment data directly from the year's trust ledgers to prepare 1099-MISC forms for owners and 1099-NEC forms for vendors paid above the IRS reporting threshold. Because the underlying ledgers were reconciled monthly, year end filing becomes a data export instead of a reconstruction project.
How quickly can an Orange County property management company start with outsourced accounting? Onboarding timelines depend on portfolio size, unit count, and how clean your current trust ledgers are, but most Orange County engagements begin with a ledger review and chart of accounts setup inside your existing software, followed by a transition month where old and new records are reconciled side by side. Ongoing reporting and three-way reconciliation typically start the following month.
Learn How REA Supports Orange County Property Management Companies
Learn how REA brings finance and accounting best practices from across the property management industry to businesses in Orange County today. Lets Connect for a free consultation and see how outsourced accounting for property management companies in Orange County fits your current software, your ownership structure, and your reporting deadlines.
Want this handled for you?
Schedule a Call